Driven to Distraction: how the car industry put a touchscreen at the centre of your dashboard — and why no one stopped it
In March 2020, the Transport Research Laboratory (TRL) published a study commissioned by road safety charity IAM RoadSmart, in partnership with the FIA Foundation and the Rees Jeffreys Road Fund. Run on TRL’s driving simulator, it tested what happened to drivers who used Apple CarPlay and Android Auto, the smartphone-projection systems now offered in most new cars, by touch and by voice while behind the wheel. When drivers selected music by touch, their reaction times slowed by more than fifty percent (57 percent with CarPlay, 53 percent with Android Auto). TRL then compared those figures with its own earlier studies on the same simulator route. It treated the comparison cautiously, since samples and methods differed, but concluded that a driver using CarPlay or Android Auto by touch was more impaired than a driver at the legal alcohol limit. IAM RoadSmart called for urgent action, the European Transport Safety Council covered it, and the automotive press noted it, briefly.
Then almost nothing happened: in the years that followed, car manufacturers went on removing physical buttons and controls from their vehicles at an accelerating pace, and the screens got larger and the menus deeper.
Tasks that once required a single physical gesture, such as turning up the heat, finding a radio station or switching on the heated seat, migrated into multi-layer software interfaces that demanded sustained visual attention to navigate. In 2022, the Swedish car magazine Vi Bilägare decided to measure what this meant in practice. It tested eleven modern cars, including a Tesla Model 3 and a BMW iX, alongside a 2005 Volvo V70, at 110 kilometres per hour on a closed airfield, asking drivers who had been given time to get to know each car to perform four common in-car tasks. The Volvo, a seventeen-year-old car with nothing but physical buttons, completed them in ten seconds. The BMW iX required 30.4 seconds. At that speed, the difference represents the car travelling the length of roughly six football pitches while the driver was still busy with the controls.
In 2024, 3,208 people died in distraction-affected crashes in the United States. The National Highway Traffic Safety Administration (NHTSA), which keeps that count, acknowledges that police-reported figures badly understate the problem; its own estimate is that distracted driving caused 12,405 deaths in 2021, more than three times the police-reported number for that year. The federal crash database has codes for distraction by a car’s own controls, but none of them isolates touchscreen infotainment as such. The data that would build the legal and political case for regulation remains thin.
How that happened runs through decisions made in carmakers’ boardrooms and through a regulatory system that chose, repeatedly and by name, not to act. It takes in the iPhone’s arrival on the dashboard, an $8 billion acquisition that imported Silicon Valley logic into the automotive supply chain, and a Chinese industrial policy that made the economics of the whole transition possible. And it has to answer a hard question: if the research was available, the risk documented and the deaths real, why did no one stop it?
Part I: Two Half-Answers
Ask most people why cars have screens instead of buttons and they will give you one of two answers. Consumers wanted them, they will say. Or: they’re cheaper to make. Both answers contain truth. But cost and demand were themselves shaped by forces further upstream, and that is where the explanation lies.
Take demand first. Showroom impressions and early reviews rewarded technology-forward interiors. But the industry’s most widely cited quality benchmark tells a different story. J.D. Power’s annual quality survey, which counts the problems owners report in their first 90 days, has repeatedly ranked infotainment as the most problematic category in new cars. It still was in 2025, when J.D. Power observed that larger touchscreens are visually appealing but their functionality is “an increasing source of frustration,” and in 2026 it was the only category that got worse. A screen’s appeal is judged in a twenty-minute test drive; its usability is discovered over months of ownership. You do not notice the ergonomic advantage of physical controls during a demonstration. You notice it at six in the morning, trying to turn down the fan on a motorway without looking away from the road.
Cost is the other half. Moving functions from physical controls to a software interface does reduce assembly complexity in meaningful ways. Physical controls can add wiring, quality-assurance checks and part numbers that must be managed across variants and markets; a screen can absorb many of those functions into a single component. The savings, however, lie mainly in logistics and line complexity rather than in component price. For much of the period of rapid screen adoption, automotive-grade displays were not cheap. What made them economically irresistible was a set of forces operating far upstream from the factory floor, in Chinese government industrial policy and the financial strategies of the world’s largest technology companies.
Why almost every new car has a screen comes down to a long list of reasons; we counted forty-four, and they are catalogued at the end of this article. Ten of them did most of the work, and the first begins with an announcement timed to the Geneva Motor Show.
Part II: The Ten Forces
The first force arrived from outside the car industry. On the morning of March 3, 2014, Apple’s press office issued a statement announcing that “leading auto manufacturers are rolling out CarPlay, the smarter, safer and more fun way to use iPhone in the car.” The launch partners named were Ferrari, Mercedes-Benz, and Volvo. The same announcement named thirteen more manufacturers that had committed to bring CarPlay to their cars. By 2022, Apple said CarPlay was available in more than 98 percent of new cars sold in the United States.
Accounts of the touchscreen transition routinely underestimate CarPlay. CarPlay is built around a screen. It can be operated through a car’s rotary knob, touchpad or buttons as well as by touch, but it presupposes a central display large enough to show its interface, and in practice most manufacturers paired it with a touchscreen. Once Apple announced the system, buyers began to expect it, because hundreds of millions of people already knew how to use an iPhone and wanted that interface in their car. Manufacturers then faced a binary choice: install a capable screen, or lose buyers to competitors who had. That part of the decision had been made for them by a technology company with no particular investment in automotive ergonomics or road safety. What remained was a choice about how to operate the screen, and it was here that the industry’s own preferences showed. Mazda proved that CarPlay could be run entirely from a rotary knob, and for years locked out its touchscreen while the car was moving. Most of its rivals did the opposite: they put the screen within reach and let the iPhone’s own gesture, the touch, become the car’s primary control. Android Auto, announced by Google in June 2014 and available in cars from 2015, created the same pressure: it too can be driven by touch or by buttons, but it needs a screen.
Before CarPlay, the industry was moving toward screens. After CarPlay, a car without a capable central display had no practical future. The shift from optional feature to table-stakes requirement can be traced to a product announcement by a company that manufactures telephones, timed to a motor show and previewed nine months earlier as “iOS in the Car” at Apple’s 2013 developer conference.
The second force made screens cheap enough to install universally, and it originated in East Asia. Throughout the 2010s, Chinese display manufacturers led by BOE Technology, CSOT and Tianma expanded their production capacity for LCD and OLED panels at a scale no competitor matched. BOE, whose largest shareholder is a Beijing state-owned capital management company, grew to become the world’s number one manufacturer of car display panels by shipment volume, a position it announced having reached in 2022. The expansion was, in substantial part, financed by the Chinese state as a matter of industrial policy. The consequence was a chronic oversupply of panels that drove prices down steeply across the decade. LG Display and Samsung Display, the Korean manufacturers that had previously led the global LCD market, found themselves unable to compete on large LCD panels and began exiting that business. Samsung Display announced its withdrawal in 2020 and ended LCD production in 2022. LG Display agreed in 2024 to sell its Guangzhou plant, its last large-size LCD factory, to TCL’s CSOT, completing the sale in 2025, while keeping LCD production for IT devices and cars.
For automotive manufacturers, falling panel prices made a large display a far smaller item in the cost of a car than it had been at the start of the decade, even though the panel is only one part of what an automotive display costs. The economics of “just put a screen there” became viable because Chinese state industrial policy had made panels cheap. The causal chain runs from a government ministry in Beijing to the dashboard of a vehicle assembled in Wolfsburg, and it almost never appears in accounts of how the screen transition happened.
The third force was corporate rather than governmental. On November 14, 2016, Samsung Electronics announced that it had agreed to acquire Harman International Industries for about $8 billion. Harman was the company behind audio brands including JBL and Harman Kardon and a leading supplier of connected-car and infotainment systems, whose technology was in more than 30 million vehicles. Samsung presented the deal as a way to accelerate its growth in automotive and connected technologies. It was the largest acquisition in Samsung’s history and, when it closed in March 2017, the largest-ever buyout by a South Korean company.
The Harman deal did something the CarPlay launch had begun but not completed: it brought consumer electronics capital, timelines, and competitive logic fully inside the automotive supply chain. Harman had supplied infotainment systems to dozens of manufacturers. Samsung now owned those supply relationships, and brought to them the iteration speed and software-first philosophy of a company whose primary business was selling smartphones. The pressure on carmakers to match consumer electronics standards of display quality, interface responsiveness, and the pace of new features became structural. Other technology companies drew the same conclusion: Intel acquired Mobileye in 2017; Qualcomm built its automotive chip business into a division projecting billions in revenue.
The fourth force, which might seem merely aesthetic, was a change of venue. For decades the car industry had made its most important reveals at motor shows in Frankfurt, Detroit and Geneva. From roughly 2014, major automotive announcements started happening at the Consumer Electronics Show in Las Vegas instead, where they were evaluated by technology press, using technology criteria. At CES, the comparison for a car’s interior is a Samsung television or an Apple iPad rather than the previous year’s Volkswagen Golf. Screen size, interface smoothness and software sophistication became the metrics by which automotive interiors were judged, because the venues in which they were judged had been designed to evaluate those things. Automotive journalism followed the venue shift. Major review outlets came to judge infotainment and connectivity as part of their verdicts, so a weak system could drag down a car’s overall review, and reviews shape the shortlists buyers draw up. Manufacturers optimising for reviews therefore had a clear incentive to invest in screen sophistication, whether or not screen sophistication had anything to do with driver safety or usability. The reviewers who wrote the scores and the editors who published them were not acting maliciously. They were responding, as institutions do, to what their readers said they wanted, and their readers had been conditioned by a decade of smartphone ownership to expect a particular kind of interface.
The fifth force was psychological. A car is an unusual consumer product in that most of the relevant information about it is invisible during the purchasing decision: how it feels to drive over time, how intuitive its controls become after three months of daily use, how much cognitive load a particular interface imposes at highway speed. What a buyer can assess in a showroom is appearance, and at that moment of first impression a large glowing screen conveys modernity and technological sophistication. Physical buttons make no such impression; their advantage shows only in use.
Economists have a term for products whose quality can be judged only through use: “experience goods,” a concept introduced by Phillip Nelson in 1970. Cars fit it well: a screen that looks appealing in the showroom can become a source of frustration in daily use. Because most buyers make their next purchase decision in a showroom, where the screen once again makes its immediate impression, that frustration may feed back into purchase decisions only weakly. The market correction mechanism that would, in a rational market, penalise poor long-term usability is likely to work slowly.
The sixth force explains why the transition became, from the manufacturer’s perspective, irreversible: a screen is also the infrastructure for a different business model.
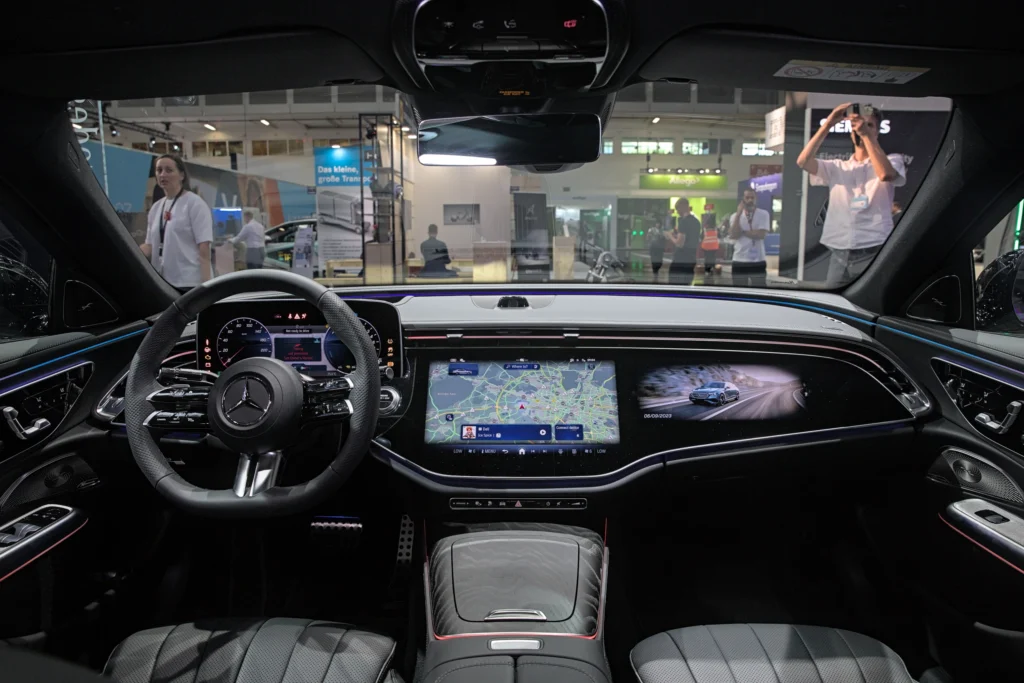
A switch wired only to its function cannot be disabled remotely, unlocked by subscription, or updated over a network; connected software can do all three. In 2022 BMW began charging subscription fees in some markets to unlock heated seats that the hardware already supported, then dropped the idea in 2023 after a customer backlash. Mercedes-Benz sells an “Acceleration Increase” for some of its electric models in the United States, as an annual subscription or a one-off payment. Cadillac’s Super Cruise driver assistance system operates on a subscription model. These moves belong to a restructuring of the automotive revenue model, from a business in which the manufacturer’s financial relationship with the customer ends at purchase to one in which the car itself is a recurring revenue platform. This restructuring depends on connected software and a screen or app through which features are sold and switched on; the decisive change is connectivity, not the removal of switches as such.
The subscription model may also help explain something that pure design logic cannot: why automotive manufacturers have resisted binding rules on screen functionality. A regulation mandating simplified infotainment interfaces, or limiting the number of functions accessible via touchscreen while moving, could constrain the screens through which many subscription features are sold and over-the-air updates are monetised. The financial stakes of interface regulation had grown considerably since the first screens appeared.
There may also be a legal dimension. When a safety-relevant function, such as cabin temperature, the rear demister or windscreen wiper speed, sits behind several software menus, a manufacturer facing litigation after a crash may find it easier to frame unsafe use as driver misuse rather than a design defect. We have found no court ruling or manufacturer document showing that this was a deliberate strategy, so it is best read as a hypothesis about incentives. If it holds, the migration of controls into screens shifted some responsibility from the designer to the driver.
The seventh force ran parallel to the subscription logic: data. A connected car collects information as well as displaying it. Taps, menu navigation and destinations entered into a navigation system all generate data about driver behaviour, routes, preferences and patterns. It is connectivity, more than the screen itself, that turns a car into a data source: location, driving behaviour, searches and feature use can all be collected. That data has proven commercial value: in January 2025 the US Federal Trade Commission took action against General Motors and OnStar, alleging that they had sold drivers’ location and driving-behaviour data, which reached insurers, without proper consent; the companies settled. The connected screen is the most visible part of that shift, from a product that was barely instrumented to one that is instrumented by design.
The eighth force was demographic and cultural, and it arrived on schedule. By 2020, millennials had overtaken baby boomers as the largest group of new-car buyers in the United States; J.D. Power dated the crossover to April 2020. It is the first generation to reach its prime car-buying years with a smartphone already in hand and a decade of daily touchscreen use behind it. For them, a rotary dial connected to a nested menu system is the legacy interface, the thing that requires learning, and a touchscreen running a smartphone-derived operating system is the familiar one. Manufacturers designing for the next decade’s primary buyer had a documented demographic reason to weight software interfaces over physical controls.
The ninth force was internal, and harder to see from outside. The car companies that survived the 2010s were not the car companies of the 1990s. They had reorganised, in many cases dramatically, around software capability, partly because the technology demanded it and partly because investors required it. Ford set up “Team Edison” in 2017 to accelerate its electric vehicles, and Volkswagen pooled its software engineers into the Car.Software Organisation in 2020, renamed CARIAD in 2021. To fill software units such as CARIAD with engineers from Google, Apple, and Amazon, manufacturers had to offer work that felt like software work. Designing a button cluster is not software work; designing a vehicle operating system, building application layers and iterating on the UI is. Nobody had to mandate the result: the people building the products had been hired to build software, and a screen gave them far more software to build than a row of buttons.
The tenth force came from the powertrain. The internal combustion vehicle is a constrained design space. A firewall separates engine from cabin. A transmission tunnel runs through the floor. Gear selectors, handbrakes, and HVAC ducting occupy fixed volumes. These physical constraints shaped dashboard architecture for a century, creating inherited positions and logic for controls that successive designers could adapt but rarely eliminate. The electric vehicle has far fewer of these constraints: a largely flat battery floor, no engine to wall off, no transmission tunnel. When Tesla designed the Model S interior, released in 2012, it had no legacy packaging to accommodate and no existing owners who expected the old layout. Car touchscreens were not new (General Motors had put one in the 1986 Buick Riviera, running the radio and climate control), but a seventeen-inch screen in the centre of a bare, flat surface, doing the work of the whole centre stack, was a choice the new packaging made easy. That decision, and the company’s subsequent rise to status symbol, established a template that every manufacturer entering EV development was then measured against.
Part III: The China Chapter
The China dimension of this story has received almost no attention in Western coverage, yet it shaped both what buyers wanted and what screens cost.
China is the world’s largest single automotive market. For Volkswagen, GM, BMW, and Mercedes-Benz, it was for years a disproportionate share of global profit as well as a large market. In 2019, for example, Volkswagen’s Chinese joint ventures earned it a proportionate operating result of €4.4 billion, reported on top of the Group’s own operating profit. China was the market that cross-subsidised product development across every other geography, although that profit pool has shrunk sharply since 2024 as Chinese brands have taken share. What Chinese consumers want, the product planners at those companies pay close attention to. And Chinese consumers place unusual weight on the digital cabin: seven in ten Chinese car owners rate infotainment “very” or “extremely” important when choosing a car, and advanced assisted driving and in-car AI are now treated as baseline expectations rather than extras.
The consequence is that when a global manufacturer designs a single platform for deployment across multiple markets, as all of them do because parallel platform development is prohibitively expensive, it designs that platform with its most important markets in mind. The platform that sells in China becomes the platform sold in Germany, the United Kingdom and the United States, and the Chinese appetite for screens travels with it.
This dynamic was then amplified by the entry of Chinese EV manufacturers. NIO, Xpeng, Li Auto, and BYD brought to market vehicles with dual screens, rotating screens, and rear passenger entertainment systems as standard equipment rather than luxury options. These brands reset the reference point for what a modern car interior looked like. When BYD became the world’s top-selling EV brand and began selling vehicles in Europe, Western manufacturers faced a specific kind of competitive pressure. Powertrain and dynamics take years to develop; interior specification can be changed within a single model cycle. The fastest way for a Western carmaker to look competitive against a Chinese rival was to install a larger screen.
The supply chain is the other half of the China story. BOE Technology, the state-backed panel maker described above, had by 2022 become the world’s leading manufacturer of automotive display panels by shipment volume, and was still first in 2024, ahead of Tianma. Its expansion, and that of its domestic rivals, was underwritten by a level of state investment that private-sector competitors in South Korea and Japan could not match. LG Display, which had been a global leader, posted operating losses of more than 2 trillion won in both 2022 and 2023 before giving up large LCD panels altogether, although it remains among the world’s five largest suppliers of automotive displays. For carmakers outside China, the panel in the dashboard went from a meaningful cost to a modest one over the course of a decade. Automotive displays had not become technically simpler; Chinese industrial policy had made the panels that constitute them cheap.
Part IV: The Body Count
The TRL study published in March 2020 put numbers on the problem. Drivers selecting music in Apple CarPlay by touch had reaction times 57 percent slower than when driving undistracted. Earlier TRL studies using the same simulator route had found that driving at the legal alcohol limit slowed reaction times by about 12 percent, although TRL cautions that samples and response methods differed between studies. Cannabis impairs by approximately 21 percent. Texting while driving, the behaviour that prompted legislation across most of the developed world, produces degradation of approximately 35 percent, still well short of selecting music by touch.
The study also found that, on the most demanding tasks, drivers spent on average up to sixteen seconds in total looking at the screen with CarPlay, and up to 29 seconds with Android Auto. At 70 mph, sixteen seconds represents more than five hundred metres travelled without meaningful attention on the road ahead.
“Driver distraction is estimated to be a factor in around a third of all road collisions in Europe each year,” said Neil Greig, IAM RoadSmart’s Policy and Research Director, when the study came out. “We’re now calling on industry and government to openly test and approve such systems and develop updated, consistent standards that genuinely help minimise driver distraction.” No such testing and approval regime followed.
Two years later, Vi Bilägare’s practical road test pointed the same way in a format accessible to any reader: a 2005 car with physical buttons was faster to operate than every modern car it tested, including a BMW iX that starts at more than £75,000 in the United Kingdom.
The tasks selected were everyday in-car interactions, not edge cases: switching on the heated seat, raising the temperature and starting the demister; tuning the radio to a station; resetting the trip computer; and dimming the instrument lighting and switching off the centre screen. One test with one group of drivers is a limited sample, and leaving out voice control may have tilted the results. Still, these were the most ordinary interactions a driver performs, and physical controls handled them far faster.
NHTSA’s official count of American deaths from distracted driving ran at about 3,200 to 3,300 a year from 2022 to 2024. Yet the agency’s own published estimate put the number of deaths caused by distracted driving in 2021 at 12,405, a figure the agency itself describes as more than three times the police-reported count. The gap exists largely because distraction is hard to prove after a crash and depends on what police officers record. NHTSA’s Fatality Analysis Reporting System has separate codes for mobile phones and for distraction by a car’s own equipment: “adjusting audio or climate controls” and “while using other component/controls integral to vehicle,” a category that explicitly includes on-board navigation. But no code isolates touchscreen infotainment as such, and many reports record only generic “distraction” or “inattention.”
How crash data is coded is itself a choice, and it has consequences: without data that isolates screen-based interfaces, the specific regulatory case is harder to make, and without that case a specific standard is harder to mandate. Thin data works in favour of the manufacturers whose products it fails to isolate.
Part V: The Institutions
The failure of regulatory institutions to respond to documented evidence of harm in the touchscreen era shows how institutional structures produce outcomes that serve the powerful without anyone in those institutions needing to be dishonest or criminal.
On April 26, 2013, NHTSA published its Visual-Manual Driver Distraction Guidelines for In-Vehicle Electronic Devices. The document is careful and thorough. It recommends that, in testing, at least 21 of 24 drivers be able to complete a task with a mean glance away from the road of no more than two seconds, no more than 15 percent of glances longer than two seconds, and no more than twelve seconds of total eyes-off-road time. It grounds these criteria in research and states the safety stakes clearly. Then it says: “NHTSA has opted to pursue nonbinding, voluntary guidelines rather than a mandatory Federal Motor Vehicle Safety Standard.” Its stated reasons were the need for more research on distraction, the pace of change in in-vehicle electronics, doubts about whether existing data could support an estimate of a rule’s benefits, and the difficulty of writing repeatable, objective test procedures for drivers who differ from one another; the choice, it added, “does not represent a decision to never issue regulations in this area.”
The document describes this as “Phase 1” of a three-phase programme. Phases 2 and 3, covering portable devices and voice interfaces, were also to be developed. The administrator who presided over Phase 1 was David Strickland, whom President Obama had nominated to lead NHTSA in December 2009 and who took office in January 2010.
Strickland left NHTSA in mid-January 2014. On January 8, days before his departure, Venable LLP, a Washington law firm, announced that he would be joining the firm as a partner, supporting its “Government Affairs, Automotive, and Technology practices.” Venable’s clients at the time included the Alliance of Automobile Manufacturers, the primary lobbying body for the auto industry in Washington, and Chrysler, then owned by Fiat. Strickland subsequently served as counsel to the Self-Driving Coalition for Safer Streets, whose members included Google, Ford, Volvo, Uber, and Lyft, before joining General Motors in October 2021 as Vice President of Global Regulatory Affairs.
Phases 2 and 3 of NHTSA’s distraction guidelines programme were never completed. Guidance for portable and aftermarket devices was published only as a draft in 2016, guidance for voice interfaces has never been issued, and all of it was voluntary in any case. The twelve-second guideline was never encoded in law. As of 2026, there is no mandatory pre-market testing requirement for automotive infotainment systems in the United States, and no federal safety standard sets a task-time or eyes-off-road limit for them; the existing standard on controls (FMVSS 101) governs the location, identification, colour and illumination of certain controls and displays, not how long they take to use. A manufacturer may, without violating any federal standard, install a system requiring thirty seconds of eyes-off-road time in a vehicle sold to the American public.
Strickland is one data point in a longer pattern: NHTSA’s senior officials have repeatedly moved into industry roles, either directly with automakers or with law firms that represent them, soon after leaving the agency. That record shows a revolving door; it cannot show any particular decision turning on it. The worry it raises is nonetheless plain: a regulator who expects a career in the industry has no need to be asked for moderation.
The liability dimension of this story connects directly to the regulatory one in a way that is rarely made explicit. If, as suggested in Part II, moving controls into software menus makes it easier to frame unsafe use as driver error, then a manufacturer has a structural reason to resist regulations that would set a measurable design standard. Mandatory interface standards, such as a maximum task complexity or required physical controls for safety-critical functions, would constrain product design. They would also re-establish a design standard against which a product could be measured in litigation, and found wanting. That incentive is inferred rather than documented, but it would help explain why the industry has not pressed for interface standards.
In Europe, the picture is different in form but similar in outcome. The EU’s General Safety Regulation, known as GSR2, adopted in late 2019 and mandatory from July 2022, is the most comprehensive vehicle safety regulation the bloc has produced in a generation. It mandated, in phases, intelligent speed assistance, autonomous emergency braking, emergency lane-keeping systems, event data recorders and an “Advanced Driver Distraction Warning” system, the last required for new vehicle types from July 2024 and for all new cars from July 2026. That last feature sounds directly relevant. It is, in practice, a camera mounted inside the vehicle to monitor the driver’s eye and head position, which warns if the driver looks away from the road. It is a system that detects distraction after the fact. What GSR2 does not contain, anywhere in its considerable length, is a requirement relating to how infotainment systems must be designed. It does incorporate UN Regulation No. 121, which fixes where certain controls go and how they are identified, coloured and lit, whether they are physical or on a screen. But on the demands an infotainment system may place on the driver, the EU’s only text remains a non-binding 2008 Commission Recommendation, the European Statement of Principles on human–machine interface. It sets no task complexity limit, no maximum eyes-off-road time for infotainment interactions and no requirement for physical controls for common functions. So the regulation meant to address driver distraction makes the car watch the driver’s eyes, but sets no limit on how often its software draws those eyes away from the road.
This omission did not go unnoticed during the regulation’s development. The European Automobile Manufacturers’ Association (ACEA), which represents most major manufacturers selling in Europe, including BMW, Mercedes-Benz, Volkswagen, Renault and Stellantis, is a registered lobbying organisation in the EU Transparency Register, a public database of interest groups that interact with EU institutions. Its president when GSR2 was adopted in 2019 was Carlos Tavares, then chief executive of PSA Group; its Director General, from October 2019, was Eric-Mark Huitema. ACEA’s public position on the automotive transition was consistently focused on electrification and digitalisation as opportunities. No public document records its position on mandatory infotainment interface standards during the GSR2 consultation. What is on the record is the regulation that emerged, and what it does not contain.
Euro NCAP, the consumer-facing safety ratings body whose five-star rating drives purchasing decisions across Europe more reliably than almost any other signal, operated throughout the years of touchscreen deployment, roughly 2012 to 2024, without meaningfully penalising vehicles for infotainment distraction risk. A car whose climate controls lived inside a touchscreen menu could receive five stars. Euro NCAP first signalled in 2024 that it would reward physical controls, and in November 2025 it published its 2026 protocols. Among the new criteria, in Euro NCAP’s words, are assessments of “the placement, clarity, and ease of use of essential controls — including the availability of physical buttons for commonly used functions.” Under the protocols, which took effect in January 2026, indicators, wipers and washer, hazard lights, horn and the eCall SOS button should be operated by a direct physical input. The change, which amounted to an institutional admission that physical controls matter for safety, came more than a decade after the Tesla Model S made a touchscreen-dominated interior mainstream in 2012.
The explanation that requires the least interpretive charity is institutional capture: an underfunded regulator, staffed by officials who expect post-government careers in the industry they regulate, operating under political pressure from an industry that employs millions in electorally significant states, will systematically under-regulate without anyone in that institution needing to make an explicit corrupt decision. NHTSA’s staff peaked at 848 full-time equivalents in FY2024 on new infrastructure funding; after the 2025 federal workforce cuts and buyouts it fell to 590 in FY2026, and the administration has requested 544 for FY2027. That is a small staff to oversee the safety of one of the world’s largest consumer industries. Its budget looks large, about $1.7 billion in FY2025, but most of it is grant money passed on to states. Of the $223 million annual General Fund appropriation for vehicle-safety operations and research, only about $70 million went directly to rulemaking, enforcement and research combined. The same account also draws on Highway Trust Fund contract authority and infrastructure-act advance appropriations, together more than twice that annual line, so the agency is not as poor as the smallest figure suggests; even so, NHTSA has itself cited funding and workforce as reasons it misses the rulemaking deadlines Congress sets, and the technology does not wait.
Throughout this period, distracted driving was framed as a behavioural problem by manufacturers, by regulators and, largely, by the media. A driver who looked at their screen was making a bad choice. The solution was education: campaigns, public service announcements, “Put the Phone Away or Pay.” The product design question, why the car required the driver to work through a screen to adjust the temperature at all, seldom reached public discussion, even though NHTSA’s own guidelines had addressed display placement, task lockouts and glance time. That framing is documented in regulatory language, in industry position papers, and in the coverage record. It also suited manufacturers, since a behavioural problem is answered with awareness campaigns rather than product recalls.
Robert Braun and Richard Randell, who study automobility at the Institute for Advanced Studies in Vienna, compare the car industry’s response to evidence of harm with the tobacco industry’s management of health evidence in the 1960s and 1970s. They argue that “similar agnotological tactics” to the tobacco industry’s, namely manufacturing doubt, funding “friendly” research and diverting debate from producers onto consumers, have been used by automobility interests, and that car harms should be tackled with tobacco-style public health policies. Their argument concerns automobility as a whole rather than infotainment specifically. The mechanism they describe is familiar: manufacture scientific ambiguity, emphasise individual responsibility, fund research that reaches more equivocal conclusions and, as the tobacco story shows, delay until the product is too deeply embedded to regulate without causing economic disruption. The pattern needs no coordination to operate, only a well-funded industry with a financial stake in the status quo, a structurally weakened regulator and a political environment in which the industry employs millions of voters.
Closing
There are signs of change. Since January 2026, Euro NCAP’s protocols have rewarded cars that keep indicators, wipers, hazard lights, horn and the eCall button on physical controls and marked down those that do not; in results published in October 2026, the BMW iX3 scored full marks for its driving controls and the Leapmotor B05 none — although physical buttons are not a condition for five stars, which the XPENG X9 still achieved with a poor controls score. Volkswagen, with the Golf facelift and the new ID. Polo, and Audi, with the new Q7, have begun restoring physical controls that were removed only years earlier, and Hyundai has pledged to keep them. Road-safety groups such as the European Transport Safety Council are now urging the European Commission to write similar requirements into the next revision of the General Safety Regulation.
Porsche shows what acting on the evidence looks like. The Taycan, unveiled in 2019, greatly reduced the number of physical switches, moving climate and many other functions onto touch surfaces. By the 2024 Cayenne, Porsche had begun restoring toggles and knobs for climate, fan speed, and volume, functions that the Taycan had moved off the centre console and into its touchscreen. Cayenne electronics manager Dirk Assfalg told The Drive in October 2025, discussing the new Cayenne Electric, that Porsches will “always” keep certain physical controls, such as the volume roller and the temperature and fan toggles, because customers strongly want them. The Drive’s headline put it more bluntly: Porsche knows it went too far. But Porsche had access to the same research and received the same customer signals as everyone else, and made a different choice.
What it leaves behind is a fleet. Hundreds of millions of vehicles, sold in the years when the research was available and the regulators did not act, are now on the roads of Europe and North America with interfaces that require their drivers to look away from the road for seconds that are, at speed, significant distances. Of the 3,208 Americans who died in distraction-affected crashes in 2024, NHTSA links 437 to crashes involving phone use. How many involved a built-in screen cannot be said with any confidence, because the crash data does not isolate touchscreen infotainment and distraction is so often recorded only in general terms.
Appendix: The Forty-Four Reasons
We counted forty-four reasons this happened. The list that follows is the analytical foundation from which this article was developed, presented as a reference document rather than a continuation of the argument above. It groups the factors (economic, regulatory, engineering, cultural, psychological, and geopolitical) that contributed to the transition from physical controls to touchscreen interfaces in passenger vehicles; it is a research tool, not an exhaustive citation list. Primary sources for the main factual claims used in the article above are identified in the Key Sources and References that follow the list.
Economics & Supply Chain
1. Software updates as a product strategy Physical controls are frozen at the moment of manufacture. Screens let manufacturers ship an unfinished product and patch it later — or add features post-sale. Tesla demonstrated that it was possible to sell features years before they functionally existed. The car stops being a finished object at the point of sale and becomes a subscription platform.
2. Cost reduction through simpler assembly The real saving is in assembly complexity. Physical controls add wiring, quality-assurance checks and part numbers for every variant; a screen can absorb many of those functions into one unit. The savings are in logistics, inventory, and line complexity rather than in the component price.
3. Localisation became easier Most dashboard controls use internationally standardised symbols (UN Regulation No. 121 and ISO 2575), but text labels, menus and feature names still vary by market. A screen changes language and content in software, which simplifies variants for a global manufacturer selling in fifty-plus countries.
4. Platform sharing across brand families Volkswagen Group sells under VW, Audi, Škoda, SEAT, Cupra, Porsche, Lamborghini and Bentley nameplates. Stellantis has fourteen brands. One screen platform deployed across many of them spreads its development cost widely. Screens allow a group to maintain the appearance of differentiation while sharing most of the underlying system. The MEB and STLA platforms both depend on this logic.
5. Warranty and repair economics A broken physical switch requires a specific replacement part. A software fault can often be fixed remotely, avoiding a workshop visit. Hardware screen module failures are often covered by replacing one unit rather than tracing a fault among many separate switches.
6. Screens consolidate repair into dealer networks A physical switch can usually be replaced by an independent garage with an ordinary part. A screen module failure more often sends the owner back to the dealer, to proprietary diagnostic software and authorised repair. It is also a growing legislative issue under right-to-repair frameworks in the US and EU.
Regulatory & Legal Dynamics
7. Fewer parts to validate Physical controls are physical parts that must be designed, validated and supplied for each variant; a screen-based control can be changed or added in software. Rules on how controls are identified (UN Regulation No. 121) apply to both, so the saving is in engineering and validation effort rather than in avoiding certification.
8. Regulatory lag on distracted driving created a permissive environment In testing, touchscreens proved significantly more cognitively demanding than physical controls, yet regulation consistently lagged deployment by roughly a decade.
9. Liability architecture — screens may shift responsibility to the driver When a feature requires deliberate navigation through multiple menus to activate, a manufacturer facing litigation may find it easier to argue driver misuse rather than design failure. No court ruling or company document we have found shows this was intended, so it is a hypothesis about incentives rather than a documented strategy. If it holds, the shift from buttons to screens moved some accident liability toward the driver.
10. The eCall mandate created connectivity infrastructure that screens could exploit The EU required eCall, automatic emergency calling, in all new types of passenger cars and light vans approved from 31 March 2018, so those cars needed an embedded cellular modem. Once that infrastructure existed, the marginal cost of a fully connected touchscreen dropped. A safety mandate inadvertently subsidised the screen transition.
Engineering Inevitabilities
11. The death of the instrument cluster as a separate control unit As processing power became cheap, it became rational to run everything through one central compute node. A screen is the output of that consolidation — an engineering inevitability once single chips that combine a computer’s main functions became powerful enough.
12. The merger of navigation and entertainment made a screen necessary Once built-in GPS navigation (introduced in 1990 and widespread by the 2000s) moved into the car, a screen was already installed. The logic of “why not put everything else here too” became difficult to resist.
13. Feature proliferation outgrew the physical dashboard Cars of the 2020s offer far more driver-adjustable functions than cars of 1990, among them driver-assistance settings, drive modes, connectivity and media options. Physical space is finite. Some consolidation onto screens was a real engineering response to growing complexity, not purely aesthetic or economic.
14. EV architecture created a design blank slate Cars with combustion engines have a firewall, engine tunnel, and transmission hump, physical constraints that shaped dash architecture for a century. Most EVs have a largely flat floor and no transmission tunnel. Early EV designers faced an emptier canvas, and a screen became the default way to fill it.
Platform & Software Strategy
15. Apple CarPlay and Android Auto mandated screens from outside the industry When Apple announced CarPlay on March 3, 2014 at the Geneva Motor Show, consumer demand for it followed quickly. CarPlay needs a central display and can be operated by touch, a rotary knob or a touchpad, so every manufacturer that wanted to offer it, eventually almost all of them, had to install a sizeable screen. The screen was forced on the industry by a technology company with no stake in automotive ergonomics; making it a touchscreen was, for most manufacturers, their own choice.
16. Subscription features use the screen as their shop window BMW’s heated seat subscription, Mercedes-Benz’s acceleration upgrade and Cadillac’s Super Cruise subscription all depend on connected software, usually sold and switched on through the car’s screen or a companion app; BMW scrapped its heated-seat subscription in 2023 after a customer backlash. Connected screens are the storefront for a different revenue model.
17. Data collection Connected cars collect detailed data on location, driving behaviour and feature use; the connected screen is the most visible part of that system. That data has established monetary value for insurance partnerships, traffic analytics, and product development.
18. Perceived differentiation with minimal engineering Changing a button layout requires retooling, while changing a screen UI requires only a software update. Brands can offer apparently different-feeling trim levels, special editions, or regional variants with almost no marginal cost.
Corporate Narrative & Investor Relations
19. The “Software Defined Vehicle” narrative was built for Wall Street From roughly 2019, major carmakers needed to present themselves to investors as technology companies rather than manufacturers, to escape the low valuation multiples applied to traditional automakers. The software-defined-vehicle narrative required screens as physical evidence. Ford, GM, Volkswagen, and Stellantis all restructured around this framing, and screens were in part a message to investors.
20. Samsung’s acquisition of Harman in 2016 brought consumer electronics logic into the supply chain Samsung announced the deal, worth about $8 billion, on November 14, 2016. It was the largest acquisition in Samsung’s history and the largest-ever buyout by a South Korean company. It restructured competitive dynamics for every infotainment supplier selling directly to carmakers. After Harman, the pressure to match consumer electronics quality and iteration velocity became structural.
21. Platform consolidation pressure from suppliers Tier-1 suppliers built large businesses around infotainment platforms and pushed OEMs toward screens because it locked in long-term software contracts. The supply chain pulled manufacturers toward screens as much as consumer demand did.
The China Factor
22. China became the world’s largest car market, with buyers who prize the digital cabin Chinese buyers place particular weight on the digital cabin. When China was among your most profitable markets, as it was for Volkswagen, whose Chinese joint ventures earned it €4.4 billion in 2019, you designed with China in mind and shipped that platform globally.
23. Chinese panel manufacturers collapsed the price of display panels BOE, CSOT, and Tianma built out massive LCD and OLED capacity — substantially financed by Chinese state investment. This created chronic oversupply that drove panel prices down steeply across the decade, forcing Korean competitors LG Display and Samsung Display out of large LCD panels. The economics of placing a large display in a vehicle became viable because Chinese industrial policy made panels cheap.
24. Chinese EV brands normalised extreme screen configurations NIO, Xpeng, Li Auto, and BYD shipped cars with dual screens, rotating screens, and rear entertainment systems as standard equipment. This reset global consumer expectations for what a modern interior looked like.
25. The competitive pressure of Chinese EVs forced Western OEMs to signal modernity quickly When BYD became the world’s top-selling EV brand and Chinese manufacturers began entering European markets, Western OEMs needed a fast, visible signal of modernity. Changing screen specification takes one model cycle, while rearchitecting a powertrain takes a decade.
26. Huawei and other Chinese tech firms raised the baseline for software capability Huawei’s HarmonyOS for cars, Baidu’s Apollo platform, and Alibaba’s AliOS created a sophisticated ecosystem that made screens functionally richer for Chinese-market vehicles, further raising global expectations.
Consumer Psychology
27. The showroom problem — purchase decisions favour screens, ownership experience does not Cars are typically decided during a twenty-minute test drive. A large screen impresses immediately. The ergonomic superiority of physical buttons is only apparent after months of daily use, after the purchase is complete. Economists call such products experience goods: the short-term impression and long-term experience diverge, and the impression weighs most at the moment of purchase.
28. Screens create an illusion of personalisation without surrendering control Wallpapers, themes, widget layouts, and drive mode displays let buyers feel they have customised their car while manufacturers retain complete control of what is configurable.
29. The psychology of perceived sophistication A clean screen surface reads as sophisticated. A dashboard with forty labelled buttons reads as complicated, even if it is functionally simpler to operate. Buyers systematically misread visual minimalism as usability. Automotive designers understood this and optimised for it.
30. Mimetic desire — Tesla made screens aspirational Once Tesla became a status symbol, its large screen became an icon of modernity. Cars without comparable screens began to feel dated, not because of any functional argument but because aspiration had attached itself to the interface. The desire was mimetic: people wanted screens because other aspirational buyers wanted screens.
31. Declining tolerance for learning curves By the mid-2010s, consumers across all age groups expected devices to be self-explanatory on first touch. Physical automotive controls had to be learned, stalk by stalk and often model by model. Screens with smartphone-derived metaphors required no learning for the basic interaction layer.
Generational & Cultural Shifts
32. The iPhone effect on buyer perception of modernity After 2007, a touchscreen became the universal shorthand for “modern.” Buyers began perceiving physical buttons as cheap or dated — even when they were functionally superior. Yet in owner surveys infotainment has repeatedly been the category owners complain about most.
33. Millennials became the primary car-buying cohort By 2020, millennials had overtaken boomers as the largest group of new-car buyers in the US. It is the first cohort to reach its prime buying years with smartphones in hand, and it finds software interfaces more natural than legacy control layouts.
34. The shift from driver-centric to passenger-centric design As driver-assistance and semi-autonomous systems proliferated, designers began conceiving the cabin as a shared space built around passengers’ screens rather than a driver’s workstation built around physical controls. The design philosophy shifted before the autonomy it assumed had arrived.
35. The autonomous driving assumption shaped interiors for a future that did not arrive From roughly 2016 to 2021, many major OEMs publicly expected high-level autonomy within a few years — Ford, for example, promised in 2016 a fully driverless car with no steering wheel or pedals by 2021. Interiors were designed for a lounge in which the driver would become a passenger. Those interiors shipped without the autonomy they were designed for.
Media & Competitive Dynamics
36. Automotive journalism created a perverse incentive loop Major automotive outlets came to judge infotainment and connectivity as part of their verdicts, so a weak system could drag down a car’s review. Manufacturers optimising for reviews had an incentive to invest in screens over ergonomics.
37. The auto show and reveal dynamic A screen-dominated interior photographs dramatically. As automotive reveals became global media events, interior design came to be optimised for the two-second impression in a reveal video or press image. Physical buttons do not create a reveal moment.
38. CES replacing auto shows as the primary reveal venue From roughly 2014, major automotive announcements migrated to the Consumer Electronics Show in Las Vegas, where they were evaluated by technology press using technology criteria, and screen size and UI sophistication became primary metrics for judging a car’s interior.
39. Competitive signalling between brands Once Mercedes-Benz installed a large screen in the S-Class, every other luxury brand faced pressure to match it. This cascaded downmarket across the following decade.
Internal Industry Dynamics
40. Interior designers gained power over UX engineers In many OEMs, dashboard control shifted toward studio designers optimising for visual minimalism and showroom impact. Flat, screen-filled surfaces photograph well, and physical buttons do not. The internal incentive structures of the companies changed.
41. The talent war for software engineers changed internal culture To attract engineers from Google, Apple, and Amazon, automakers had to offer software work. Physical button design does not attract software engineers. This tilted product decisions toward software in organisations whose design culture was being reshaped by hiring requirements.
42. The assumption that voice would solve the usability problem Most OEMs made a bet that voice control would mature quickly enough to compensate for the loss of tactile controls. It did not mature in time, and by then the dashboards were already committed. Volvo, for one, has said that voice control rather than buttons is its answer for use on the road.
43. Tesla’s direct sales model had an overlooked UX consequence Without dealerships, Tesla could not rely on a salesperson to explain a complex control layout. The car arguably needed to be more self-explanatory. A screen with menus and smartphone metaphors, which buyers already knew, solved that onboarding problem.
The Central Irony
44. The distracted driving paradox — screens are the problem they were sold as solving In-car screens were positioned as a safety improvement over reaching for a phone. The TRL study commissioned by IAM RoadSmart found that selecting music by touch in Apple CarPlay or Android Auto slowed reaction times more than driving at the legal alcohol limit. Carmakers kept moving controls onto screens after the research was published.
Disclaimer:
Tesla and the Tesla logo are used here solely for identification, commentary, and criticism in an editorial context. No affiliation with, sponsorship by, or endorsement from Tesla, Inc. is claimed or implied.
Gen AI Disclaimer
Some contents of this page were generated and/or edited with the help of a Generative AI.
Media
Mercedes-Benz W214 at IAA 2023 – Wikipedia
Key Sources and References
TRL/IAM RoadSmart Infotainment Study
Ramnath, R., Kinnear, N., Chowdhury, S. & Hyatt, T. Interacting with Android Auto and Apple CarPlay when driving: The effect on driver performance (Report PPR948). Transport Research Laboratory; report dated 31 January 2020, published March 2020. Commissioned by IAM RoadSmart in partnership with the FIA Foundation and the Rees Jeffreys Road Fund. Full report (PDF), trl.co.uk https://www.trl.co.uk/uploads/trl/documents/PPR948-_IAM-RoadSmart—infotainment-sim-study.pdf
IAM RoadSmart. Infotainment campaign page. iamroadsmart.com https://www.iamroadsmart.com/infotainment/
Road Safety GB (17 March 2020). Research highlights ‘serious concerns’ about in-car technology (Neil Greig quotes). roadsafetygb.org.uk https://roadsafetygb.org.uk/news/research-highlights-serious-concerns-about-in-car-technology/
European Transport Safety Council (2020). Apple CarPlay and Android Auto infotainment systems weaken reactions more than alcohol and cannabis. etsc.eu https://etsc.eu/apple-carplay-and-android-auto-infotainment-systems-weaken-reactions-more-than-alcohol-and-cannabis/
WardsAuto (2020). Distraction study calls out touchscreens (reaction-time and glance figures). wardsauto.com https://www.wardsauto.com/news/archive-wards-distraction-study-calls-out-touchscreens/794229/
Vi Bilägare HMI Test
Vi Bilägare (17 August 2022). Physical buttons outperform touchscreens in new cars, test finds. Vi Bilägare describes itself as Sweden’s biggest car magazine. Method: 11 modern cars plus a 2005 Volvo V70 (12 in total) at 110 km/h on an airfield; four timed tasks; drivers given familiarisation time. vibilagare.se https://www.vibilagare.se/nyheter/physical-buttons-outperform-touchscreens-new-cars-test-finds
Top Gear (2022). Swedish test finds car touchscreens are worse than buttons. topgear.com https://www.topgear.com/car-news/swedish-test-finds-car-touchscreens-are-worse-buttons
The Autopian (2022). Swedish test offers compelling evidence that buttons are less distracting than touchscreen infotainment systems (sample-size and voice-control caveats). theautopian.com https://www.theautopian.com/swedish-test-offers-compelling-evidence-that-buttons-are-less-distracting-than-touchscreen-infotainment-systems/
Auto123 (2022). Touchscreens vs buttons study. auto123.com https://www.auto123.com/en/news/touchscreens-buttons-study-distraction-driving/69529/
Autocar (2025). BMW iX review (UK prices from £75,405). autocar.co.uk https://www.autocar.co.uk/car-review/bmw/ix
NHTSA Distracted Driving Statistics and Crash Coding
NHTSA (2026). Distracted Driving in 2024, Research Note DOT HS 813 790 (3,208 killed; 437 in crashes involving phone use; Table A-1 “Driver Distracted By” codes). crashstats.nhtsa.dot.gov https://crashstats.nhtsa.dot.gov/Api/Public/ViewPublication/813790
NHTSA (2025). Distracted Driving in 2023, Research Note DOT HS 813 703 (3,275 killed as first reported). crashstats.nhtsa.dot.gov https://crashstats.nhtsa.dot.gov/Api/Public/ViewPublication/813703
NHTSA (2024). 2022 traffic deaths and 2023 early estimates (3,308 distraction deaths in 2022). nhtsa.gov https://www.nhtsa.gov/press-releases/2022-traffic-deaths-2023-early-estimates
NHTSA (5 January 2024). Advanced Impaired Driving Prevention Technology, advance notice of proposed rulemaking, 89 FR 830 (12,405 estimated distraction deaths in 2021). federalregister.gov https://www.federalregister.gov/documents/2024/01/05/2023-27665/advanced-impaired-driving-prevention-technology
Smart Cities Dive (2 April 2024). Traffic deaths declined in 2023, but distracted driving remains a danger. smartcitiesdive.com https://www.smartcitiesdive.com/news/traffic-deaths-distracted-driving-danger-nhtsa/711890/
NHTSA. FARS User’s Guide (2012), data element “Driver Distracted By” (codes for audio/climate controls and other integral controls, including on-board navigation). nber.org mirror (PDF) https://nber.org/fars/ftp.nhtsa.dot.gov/FARS/FARS-DOC/USERGUIDE-2012.pdf
National Safety Council. Injury Facts: distracted driving. injuryfacts.nsc.org https://injuryfacts.nsc.org/motor-vehicle/motor-vehicle-safety-issues/distracted-driving/
NHTSA Distraction Guidelines and US Standards
NHTSA (26 April 2013). Visual-Manual NHTSA Driver Distraction Guidelines for In-Vehicle Electronic Devices, 78 FR 24818, Docket No. NHTSA-2010-0053 (acceptance criteria; “NHTSA has opted to pursue nonbinding, voluntary guidelines rather than a mandatory Federal Motor Vehicle Safety Standard”). federalregister.gov https://www.federalregister.gov/documents/2013/04/26/2013-09883/visual-manual-nhtsa-driver-distraction-guidelines-for-in-vehicle-electronic-devices
NHTSA (5 December 2016). Visual-Manual NHTSA Driver Distraction Guidelines for Portable and Aftermarket Devices (draft, Phase 2). federalregister.gov https://www.federalregister.gov/documents/2016/12/05/2016-29051/visual-manual-nhtsa-driver-distraction-guidelines-for-portable-and-aftermarket-devices
49 CFR 571.101, FMVSS No. 101: Controls and displays. ecfr.gov https://www.ecfr.gov/current/title-49/subtitle-B/chapter-V/part-571/subpart-B/section-571.101
Apple CarPlay and Android Auto
Apple (3 March 2014). Apple Rolls Out CarPlay. apple.com https://www.apple.com/newsroom/2014/03/03Apple-Rolls-Out-CarPlay-Giving-Drivers-a-Smarter-Safer-More-Fun-Way-to-Use-iPhone-in-the-Car/
Apple Support. Use CarPlay with your iPhone (touchscreen, rotary knob or touchpad control). support.apple.com https://support.apple.com/en-gb/HT205634
MacRumors. Review: Mazda’s CarPlay support (CarPlay operated with the Commander knob). macrumors.com https://www.macrumors.com/review/mazda-carplay
Mazda Connect owner’s manual. Touch Panel Operation (Some Models): touch operation for Apple CarPlay/Android Auto only, with a “Touchscreen in Motion” setting. mazdausa.com https://www.mazdausa.com/static/manuals/mazdaconnect-2/contents/2701988363.html
Autoblog (10 June 2013). Apple unveils iOS for the car. autoblog.com https://www.autoblog.com/2013/06/10/apple-unveils-ios-for-the-car/
Motoring Research (2022). Apple CarPlay WWDC 2022 update (CarPlay in more than 98 percent of new US cars). motoringresearch.com https://www.motoringresearch.com/car-news/apple-carplay-wwdc-2022-update/
AutoGuide (2015). 2015 Hyundai Sonata is first car to offer Android Auto. autoguide.com https://www.autoguide.com/auto-news/2015/05/2015-hyundai-sonata-is-first-car-to-offer-android-auto.html
Display Industry: BOE, LG Display and Samsung Display
BOE. Automotive display (BOE’s own claim of No. 1 in 2022). boe.com https://www.boe.com/en/solution/AutomotiveDisplay
Omdia (March 2025). Global automotive display panel shipments reach 232 million units in 2024 (BOE first; LG Display among the top five). omdia.tech.informa.com https://omdia.tech.informa.com/pr/2025/mar/omdia-global-automotive-display-panel-shipments-reach-232-million-units-in-2024-fueled-by-chinas-market-influence
Yicai Global. BOE Technology’s two major shareholders plan to dump shares (Beijing State-owned Capital Management Center as top shareholder). yicaiglobal.com https://yicaiglobal.com/news/boe-technology-two-major-shareholders-plan-to-dump-shares-worth-up-to-usd600-million
BOE Technology Group (29 August 2026). Interim Report 2026 (Summary), shareholder table (Beijing State-owned Capital Operation and Management Company Limited, 10.97%). szse.cn (PDF) https://disc.static.szse.cn/disc/disk03/finalpage/2026-08-29/19d8eb5a-02c6-43ea-a61f-169b00edc3b9.PDF
Yole Group. LG, Samsung and others: the battle for next-generation TV displays. yolegroup.com https://www.yolegroup.com/?p=160875
Digitimes (13 June 2022). Report on Samsung Display ending LCD production in June 2022. digitimes.com https://www.digitimes.com/news/a20220613PD203.html
The Korea Times (27 September 2024). LG Display signs $1.5 bil. deal to sell large LCD plant in Guangzhou. koreatimes.co.kr https://www.koreatimes.co.kr/amp/business/companies/20240927/lg-display-signs-15-bil-deal-to-sell-large-lcd-plant-in-guangzhou
SVC (2025). LG Display to sell final LCD plant in China. svconline.com https://www.svconline.com/proav-today/lg-display-to-sell-final-lcd-plant-in-china
KED Global (2024). LG Display to pull out of LCD business (losses; Chinese state subsidies). kedglobal.com https://www.kedglobal.com/electronics/newsView/ked202402200013
Samsung/Harman Acquisition and Technology-Industry Entry
Samsung Newsroom (14 November 2016). Samsung Electronics to Acquire HARMAN, Accelerating Growth in Automotive and Connected Technologies. news.samsung.com https://news.samsung.com/global/samsung-electronics-to-acquire-harman-accelerating-growth-in-automotive-and-connected-technologies
Harman International Industries, Incorporated (10 March 2017). SEC Form 8-K on completion of the merger with Samsung Electronics, approximately $8.02 billion total purchase price. sec.gov https://www.sec.gov/Archives/edgar/data/800459/000119312517078968/d184457d8k.htm
TechCrunch (13 November 2016). Samsung is buying Harman for $8B. techcrunch.com https://techcrunch.com/2016/11/13/samsung-harman/
The Investor (March 2017). Largest-ever buyout by a South Korean company. theinvestor.co.kr https://www.theinvestor.co.kr/article/1263984
Engadget (2017). Intel’s acquisition of Mobileye is officially complete. engadget.com https://www.engadget.com/2017-08-08-intel-acquisition-mobileye-complete.html
PCWorld (2016). Forget the gadgets: come to CES 2016 for the cars. pcworld.com https://www.pcworld.com/article/418888/forget-the-gadgets-come-to-ces-2016-for-the-cars.html
Engadget (2019). While we were looking at 3D TVs, CES morphed into an auto show. engadget.com https://www.engadget.com/2019/01/04/ces-auto-show/
Quality, Consumers and Demographics
J.D. Power via Business Wire (26 June 2025). Fewer Physical Vehicle Controls and More Problematic Touchscreen Make Infotainment System a Modern Catch-All Drawer. businesswire.com https://www.businesswire.com/news/home/20250626729527/en/Fewer-Physical-Vehicle-Controls-and-More-Problematic-Touchscreen-Make-Infotainment-System-a-Modern-Catch-All-Drawer-J.D.-Power-Finds
J.D. Power (2025). 2025 U.S. Initial Quality Study. jdpower.com https://www.jdpower.com/business/press-releases/2025-us-initial-quality-study-iqs
J.D. Power (2026). 2026 U.S. Initial Quality Study (infotainment the only category to worsen). jdpower.com https://www.jdpower.com/business/press-releases/2026-us-initial-quality-study-pr/
Nelson, P. (1970). Information and Consumer Behavior. Journal of Political Economy, 78(2), 311–329. DOI 10.1086/259630 https://www.doi.org/10.1086/259630
CNBC (10 December 2021). Millennials overtake boomers, Gen X as biggest buyers of pickup trucks (J.D. Power: millennials the largest group of new-vehicle buyers since April 2020). cnbc.com https://www.cnbc.com/amp/2021/12/10/millennials-overtake-boomers-gen-x-as-biggest-buyers-of-pickup-trucks-in-us-for-first-time.html
Dacia UK. Sandero multimedia (smartphone-based Media Control instead of a built-in screen). dacia.co.uk https://www.dacia.co.uk/vehicles/sandero/multimedia.html
Subscriptions, Data and Software Organisations
WhichCar (2023). BMW rolls back on heated seat subscriptions. whichcar.com.au https://whichcar.com.au/news/bmw-rolls-back-on-heated-seat-subscriptions
InsideEVs (2023). Mercedes debuts Acceleration Increase subscription for EQE and EQS. insideevs.com https://insideevs.com/news/664391/mercedes-debuts-acceleration-increase-subscription-eqe-eqs/
GM Authority (January 2026). GM Super Cruise subscriptions rising according to plan. gmauthority.com https://gmauthority.com/blog/2026/01/gm-super-cruise-subscriptions-rising-according-to-plan/
TechCrunch (14 January 2026). The FTC’s data-sharing order against GM is finally settled. techcrunch.com https://techcrunch.com/2026/01/14/the-ftcs-data-sharing-order-against-gm-is-finally-settled
Electrek (2 October 2017). Ford forms Team Edison to accelerate electric car programs. electrek.co https://electrek.co/2017/10/02/ford-new-team-edison-accelerate-electric-car-programs/
CARIAD (2021). Car.Software Organisation is now CARIAD. cariad.technology https://cariad.technology/de/en/news/stories/car-software-organisation-is-now-cariad.html
Tesla, Electric Vehicles and Autonomy
NBC News (2012). Report on the debut of the Tesla Model S’s 17-inch dashboard display. nbcnews.com https://www.nbcnews.com/tech/gadgets/teslas-fancy-17-inch-lcd-dashboard-makes-its-debut-alongside-flna839914
Jalopnik (2019). The Porsche Taycan was designed with something called “foot garages.” jalopnik.com https://jalopnik.com/the-porsche-taycan-was-designed-with-something-called-f-1836023684
InsideEVs. The Tesla direct sales vs franchised dealership battle is far from resolution. insideevs.com https://insideevs.com/news/333376/the-tesla-direct-sales-vs-franchised-dealership-battle-is-far-from-resolution/
FOX 2 Detroit (2016). Ford says it will have fully autonomous car by 2021. fox2detroit.com https://www.fox2detroit.com/news/ford-says-it-will-have-fully-autonomous-car-by-2021
China
Volkswagen AG. Annual Report 2019: Volkswagen Group China (€4.4 billion proportionate operating result of the Chinese joint ventures). volkswagenag.com https://annualreport2019.volkswagenag.com/divisions/volkswagen-group-china.html
Caixin Global (11 March 2026). Volkswagen struggles with tariffs, China slump as profit tumbles. caixinglobal.com https://www.caixinglobal.com/2026-03-11/volkswagen-struggles-with-tariffs-china-slump-as-profit-tumbles-102421882.html
Business Standard / AP (December 2024). China losses force GM to take $5 bn restructuring charge. business-standard.com https://www.business-standard.com/amp/companies/news/china-losses-force-gm-to-take-5-bn-restructuring-charge-cut-assets-value-124120400942_1.html
McKinsey (2026). Launch of China Auto Consumer Survey, 2026. mckinsey.com https://www.mckinsey.com/cn/updates/launch-of-china-auto-consumer-survey-2026
Counterpoint Research. Survey: 7 in 10 car owners in China consider their vehicles a second living room. counterpointresearch.com https://counterpointresearch.com/default.htm/insights/Survey-7-in-10-Car-Owners-in-China-Consider-Their-Vehicles-as-Second-Living-Room-for-Entertainment-Relaxation-Connectivity
CnEVPost (2 January 2024). BYD overtakes Tesla in quarterly battery-electric sales. cnevpost.com https://cnevpost.com/2024/01/02/byd-beats-tesla-quarterly-bev-sales/
Electrek (2 January 2026). BYD outsells Tesla in all-electric cars for 2025. electrek.co https://electrek.co/2026/01/02/byd-crushes-tesla-all-electric-sales-for-2025-secures-global-bev-crown/
David Strickland / Revolving Door
Transport Topics (2009). Obama nominates Senate aide Strickland to become next NHTSA administrator. ttnews.com https://www.ttnews.com/articles/obama-nominates-senate-aide-strickland-become-next-nhtsa-administrator
Safety+Health (2009). Senate confirms Strickland as NHTSA administrator. safetyandhealthmagazine.com https://www.safetyandhealthmagazine.com/articles/senate-confirms-strickland-as-nhtsa-administrator-2
Venable LLP (8 January 2014). NHTSA Administrator David L. Strickland to join DC regulatory group. venable.com https://www.venable.com/about/news/2014/01/nhtsa-administrator-david-l-strickland-to-join-dc
Streetsblog USA (10 January 2014). NHTSA chief David Strickland gets caught in the revolving door. usa.streetsblog.org https://usa.streetsblog.org/2014/01/10/nhtsa-chief-david-strickland-gets-caught-in-the-revolving-door
Safety Research & Strategies. Strickland takes express to Lobbytown (Venable’s auto-industry clients). safetyresearch.net https://www.safetyresearch.net/strickland-takes-express-to-lobbytown/
Center for Auto Safety (2014). Automakers stay cozy in US capital. autosafety.org https://www.autosafety.org/automakers-stay-cozy-us-capital/
TechCrunch (26 April 2016). Google, Uber, Lyft join automakers in self-driving car lobby. techcrunch.com https://techcrunch.com/2016/04/26/google-uber-lyft-join-automakers-in-self-driving-car-lobby/
GM Newsroom (2021). GM names David Strickland VP, Global Regulatory Affairs. news.gm.com https://news.gm.com/home.detail.html/Pages/news/us/en/2021/sep/0922-strickland.html
EU Regulation
Regulation (EU) 2019/2144 (General Safety Regulation). EUR-Lex · legislation.gov.uk copy https://eur-lex.europa.eu/legal-content/EN/ALL/?uri=CELEX:32019R2144 · https://www.legislation.gov.uk/eur/2019/2144/contents
Thatcham Research. Thatcham Research explains new EU vehicle safety regulation (phase-in dates, including ADDW 2024/2026). thatcham.org https://www.thatcham.org/thatcham-research-explains-new-eu-vehicle-safety-regulation-and-what-it-means-for-uk-drivers/
Commission Recommendation 2008/653/EC, European Statement of Principles on human–machine interface (non-binding). EUR-Lex https://eur-lex.europa.eu/eli/reco/2008/653/oj
Regulation (EU) 2015/758 (eCall; new vehicle types from 31 March 2018). legislation.gov.uk copy https://www.legislation.gov.uk/eur/2015/758/contents
UN Regulation No. 121 (location and identification of hand controls, tell-tales and indicators). UNECE text (PDF), mlit.go.jp https://www.mlit.go.jp/jidosha/un/UN_R121.pdf
Euro NCAP 2026 Protocols
New Mobility (8 March 2024). Euro NCAP to punish manufacturers for excessive touchscreen controls. newmobility.news https://newmobility.news/en/2024/03/08/euro-ncap-to-punish-manufacturers-for-excessive-touchscreen-controls/
Euro NCAP (26 November 2025). Euro NCAP announces 2026 protocol changes to tackle modern driving risks. euroncap.com https://www.euroncap.com/press-media/euro-ncap-announces-2026-protocol-changes-to-tackle-modern-driving-risks/
Euro NCAP (12 October 2026). Buttons are back for basic functions, Euro NCAP confirms in testing (driving-control scores). euroncap.com https://www.euroncap.com/press-media/buttons-are-back-for-basic-functions-euro-ncap-confirms-in-testing/
Euro NCAP (2026). A new benchmark for vehicle safety: BMW and ZEEKR secure five stars under Euro NCAP’s new tests. euroncap.com https://www.euroncap.com/press-media/a-new-benchmark-for-vehicle-safety-bmw-and-zeekr-secure-five-stars-under-euro-ncap-s-new-tests/
European Transport Safety Council (2026). Euro NCAP new 2026 protocols target distraction, impairment and speeding. etsc.eu https://etsc.eu/euro-ncap-new-2026-protocols-target-distraction-impairment-and-speeding/
ACEA and EU Lobbying
ACEA. Transparency (EU Transparency Register ID 0649790813-47). acea.auto · LobbyFacts https://www.acea.auto/transparency/ · https://lobbyfacts.eu/representative/86a5950213e247c9b97d4d0b58a0bcad/association-des-constructeurs-europens-d-automobiles
ACEA. Carlos Tavares re-elected ACEA President for 2019. acea.auto https://www.acea.auto/press-release/carlos-tavares-re-elected-acea-president-for-2019/
ACEA. BMW CEO Zipse to lead ACEA next year (president for 2021). acea.auto https://www.acea.auto/press-release/bmw-ceo-zipse-to-lead-acea-next-year/
ACEA (2019). ACEA appoints new Director General (Eric-Mark Huitema, from 1 October 2019). acea.auto https://www.acea.auto/press-release/acea-appoints-new-director-general/
ACEA (2024). ACEA presidency transitions to new mandate as Stellantis membership approved. acea.auto https://www.acea.auto/press-release/acea-presidency-transitions-to-new-mandate-as-stellantis-membership-approved/
University of Utah / David Strayer Research
Strayer, D.L., Cooper, J.M., Goethe, R.M., McCarty, M.M., Getty, D.J. & Biondi, F. (2017). Visual and Cognitive Demands of Using In-Vehicle Information Systems. AAA Foundation for Traffic Safety. Background source: in-vehicle infotainment tasks imposed high or very high demand on drivers in 23 of the 30 model-year 2017 vehicles tested, with navigation programming the most demanding task. aaafoundation.org https://aaafoundation.org/visual-cognitive-demands-using-vehicle-information-systems/
University of Utah news summary. psych.utah.edu https://psych.utah.edu/news/strayer-infotainment-dangerous.php
NHTSA Staffing and Budget
Congressional Research Service (July 2025). Department of Transportation Funding: FY2021–FY2025 Enacted and FY2026 Requested (R48596). Confirms 620 FTEs in FY2021, 751 in FY2023 and 848 in FY2024; NHTSA annual (General Fund) Operations & Research appropriation of $223 million enacted in FY2025, of which rulemaking $21.2 million, enforcement $19.3 million and research and analysis $29.8 million (Table 10); separate Highway Trust Fund contract authority for Operations & Research of $205.4 million and IIJA advance appropriations of $321.7 million. congress.gov (PDF) https://www.congress.gov/crs_external_products/R/PDF/R48596/R48596.4.pdf
Congressional Research Service (2026). Department of Transportation FY2027 Funding Request (R48947): 590 FTEs in FY2026; 544 requested for FY2027. congress.gov https://www.congress.gov/crs-product/R48947
GM Authority (February 2025). NHTSA workforce cut by 4 percent. gmauthority.com https://gmauthority.com/blog/2025/02/nhtsa-workforce-cut-by-4-percent/
GM Authority (July 2025). NHTSA to cut 25 percent of its workforce: report. gmauthority.com https://gmauthority.com/blog/2025/07/nhtsa-to-cut-25-percent-of-its-workforce-report/
Tobacco Industry Comparison — Peer-Reviewed Sources
Braun, R. and Randell, R. (2025). “Automobility violence: the case for adopting tobacco public health policies.” Applied Mobilities, 10(3), pp. 329–351. Published online March 12, 2025. DOI 10.1080/23800127.2025.2477939 · open-access author copy (IHS) https://doi.org/10.1080/23800127.2025.2477939 · https://irihs.ihs.ac.at/id/eprint/7148/1/braun-randell-2025-automobility-violence-tobacco-public-health-policies.pdf
Miner, P., Smith, B.M., Jani, A., McNeill, G. and Gathorne-Hardy, A. (2024). “Car harm: A global review of automobility’s harm to people and the environment.” Journal of Transport Geography, 115, 103817. Background on the scale of automobility’s harms; does not discuss tobacco. sciencedirect.com https://www.sciencedirect.com/science/article/pii/S0966692324000267
Physical Controls Return: Porsche, Volkswagen, Hyundai, Volvo
The Drive (8 October 2025). Porsche knows it went too far ditching buttons and knobs in the Taycan (interview with Cayenne electronics manager Dirk Assfalg about the Cayenne Electric; “went too far” is The Drive’s headline wording). thedrive.com https://www.thedrive.com/news/porsche-knows-it-went-too-far-ditching-buttons-and-knobs-in-the-taycan
Porsche Newsroom (2019). Digital, clear, sustainable: the interior of the new Porsche Taycan. newsroom.porsche.com https://newsroom.porsche.com/en/2019/products/porsche-taycan-interior-digital-clear-sustainable-18432.html
Porsche Newsroom (2024). From customer feedback to series production (individual button changes). newsroom.porsche.com https://newsroom.porsche.com/en/2024/company/porsche-customer-feedback-jd-power-study-37921.html
CompleteCar.ie (2023). Porsche Cayenne gets big refresh. completecar.ie https://completecar.ie/car-news/article/12335/Porsche-Cayenne-gets-big-refresh
Slate (April 2023). Overview of manufacturers restoring buttons. slate.com https://slate.com/business/2023/04/cars-buttons-touch-screens-vw-porsche-nissan-hyundai.html
InsideEVs (2023). VW will bring back physical buttons in new cars. insideevs.com https://insideevs.com/news/701296/vw-physical-controls-to-return/
Motor1 (2023). Hyundai pledges to keep physical buttons. motor1.com https://www.motor1.com/news/658027/hyundai-pledges-keep-physical-buttons/
The Drive. The Volvo EX90 electric SUV won’t have buttons, just screens (Volvo backs voice control). thedrive.com https://www.thedrive.com/news/the-volvo-ex90-electric-suv-wont-have-buttons-just-screens
Appendix Background
Japanese Nostalgic Car. Mitsubishi Electric, which put the world’s first in-car GPS in the 1990 Mazda Cosmo. japanesenostalgiccar.com https://japanesenostalgiccar.com/mitsubishi-electric-mazda-eunos-cosmo-jc-ccs-gps/
Volkswagen Group Annual Report 2025: New Group models in 2025. volkswagen-group.com https://annualreport2025.volkswagen-group.com/group-management-report/business-development/new-group-models-in-2025.html
Carscoops (October 2024). Stellantis to review the future of its 14 brands. carscoops.com https://www.carscoops.com/2024/10/stellantis-to-review-the-future-of-its-14-brands-by-2026-says-ceo/
Repairer Driven News (2020). Massachusetts voters approve telematics data access in new ‘Right to Repair’ push. repairerdrivennews.com https://www.repairerdrivennews.com/2020/11/04/mass-voters-approve-telematics-data-access-in-new-right-to-repair-push/
Tesla Support. Full Self-Driving (Supervised). tesla.com https://www.tesla.com/en_AU/support/fsd
GM News (19 March 2025). Retro Rides: The 1986 Buick Riviera (with a cool touch screen) (Graphic Control Center touchscreen for radio and climate). news.gm.com https://news.gm.com/home.detail.html/Pages/topic/us/en/2025/mar/0319-retrorides.html
AutoGuide (2013). 2014 Mercedes S-Class photos show full cabin. autoguide.com https://www.autoguide.com/auto-news/2013/05/2014-mercedes-s-class-photos-show-full-cabin-car.html
S&P Global AutoTechInsight (2021). Huawei launches HarmonyOS-powered smart cockpit solution. spglobal.com https://autotechinsight.spglobal.com/news/5260995/huawei-launches-harmonyos-powered-smart-cockpit-solution